How to calculate CAC payback period
About
Zach Strauss is the founder of CapitalGTM, a Columbus B2B marketing agency built for pipeline, not posts. A three-time exited operator and four-time Inc. 5000 honoree, he brings Fortune 2000 enterprise sales experience to building revenue engines for B2B companies in the $5M to $50M range.
Experience Highlights
- 3x successful company exits
- 4x Inc. 5000 honoree
- Fortune 2000 enterprise sales background
- Built GTM systems for B2B SaaS, industrial services, healthtech
Areas of Expertise
CAC payback period is the single most important number in B2B marketing budget decisions. The formula is simple. The inputs are where most companies get it wrong.
Every B2B founder claims to track CAC payback. Most of them are tracking something else. The most common error is calculating CAC using only marketing spend, ignoring sales costs, and producing a number that looks healthy while actual unit economics are broken. Companies make budget decisions on the wrong number and wonder why growth stalls.
This article walks through how to calculate CAC payback period correctly, what the healthy ranges are by B2B model, how to use the number to make better marketing budget decisions, and what to do when CAC payback is broken. The framework is simple enough to apply this week and rigorous enough to actually be useful.
If you have read our piece on B2B marketing budget, this is the math underneath it. CAC payback is the right framework for marketing budget decisions because it forces you to think about unit economics rather than industry averages. CapitalGTM's RevOps practice is built around getting these numbers right.
- The formula is simple. The inputs are the hard part.: CAC payback equals total acquisition cost divided by monthly gross profit per customer. The math is one division. The hard part is calculating CAC correctly.
- Most B2B companies miscalculate CAC by 30-60%: The most common errors: excluding sales costs, using contribution margin instead of gross margin, and missing fully-loaded marketing overhead. Bad inputs produce useless outputs.
- Healthy ranges depend on your B2B model: B2B SaaS: 12-18 months on MRR. B2B services: 6-12 months. Industrial B2B: 18-36 months. Use the right benchmark for your motion.
- CAC payback over 24 months is a warning sign: In most B2B categories, CAC payback over 24 months indicates a broken funnel rather than a budget problem. More spend will not fix it.
- Track CAC payback monthly, not annually: Annual CAC payback hides quarterly variation that often signals deeper unit economic problems. Monthly tracking surfaces problems early enough to fix them.
The formula
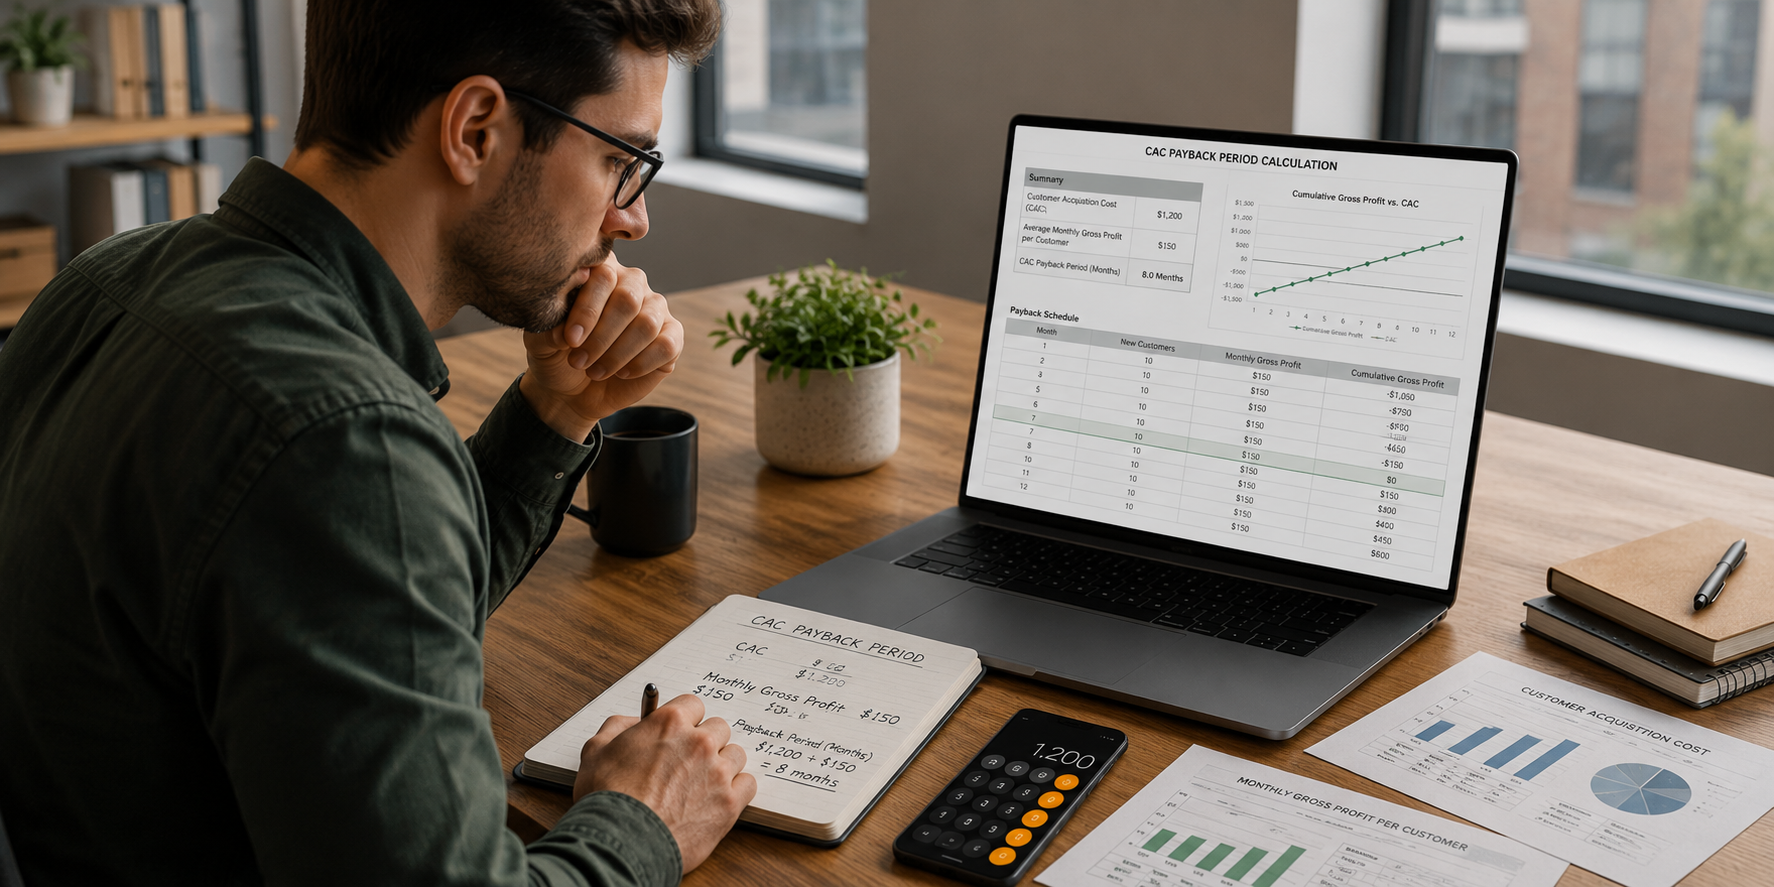
CAC payback period in months equals total customer acquisition cost divided by monthly gross profit per customer.
CAC Payback = CAC / (Monthly Revenue per Customer × Gross Margin %)
For B2B SaaS, monthly revenue per customer is MRR (monthly recurring revenue). For B2B services with one-time or multi-month contracts, monthly revenue per customer equals total contract value divided by contract length in months.
The output is the number of months required to recover your acquisition investment through the gross profit that customer generates. Lower is better, with the exact threshold depending on your B2B model.
The formula itself is straightforward. The work is in calculating CAC correctly.
Calculating CAC correctly
Total CAC includes every cost associated with acquiring a new customer, divided by new customers acquired in the same period. The components are usually broken into Sales and Marketing.
Marketing CAC components: fully-loaded marketing headcount (salary plus benefits plus equity plus overhead allocation), paid media spend, content production costs (in-house or freelance), marketing tools and platforms (HubSpot, Marketo, etc.), agency fees, events and field marketing, creative and design costs.
Sales CAC components: fully-loaded sales headcount (AEs, SDRs, sales engineers), sales commissions and bonuses, sales tools (Salesforce, Outreach, Gong, etc.), sales-specific overhead (CRM, sales operations), sales travel and entertainment.
Add Marketing CAC and Sales CAC together for total CAC, then divide by new customers acquired in the period.
Common errors: counting only paid media (excludes 60-80 percent of real CAC), excluding sales commissions (understates CAC by 10-20 percent), excluding fully-loaded headcount (understates by 30-50 percent), excluding overhead allocation (understates by 5-15 percent). Cumulatively, these errors can produce a reported CAC that is 40-60 percent below the real number.
| Cost category | Include in CAC? | Notes |
|---|---|---|
| Paid media spend | Yes | Direct acquisition spend |
| Marketing headcount (loaded) | Yes | Salary + benefits + equity + overhead |
| Sales headcount (loaded) | Yes | AEs, SDRs, sales engineers |
| Sales commissions | Yes | Often missed, but real CAC |
| Marketing tools | Yes | HubSpot, automation, analytics |
| Sales tools | Yes | Salesforce, Outreach, etc. |
| Content production | Yes | In-house or freelance |
| Agency fees | Yes | Both marketing and sales agencies |
| Customer success | No | CS supports retention, not acquisition |
| Implementation services | No | Cost of revenue, not acquisition |
Getting gross margin right
The denominator in CAC payback uses gross margin, not contribution margin or net margin. Gross margin equals revenue minus cost of goods sold (COGS), divided by revenue.
For B2B SaaS: COGS includes hosting and infrastructure, third-party software licenses bundled into the product, customer support (some companies allocate this here, some to OpEx), and any direct cost of delivering the product. Typical B2B SaaS gross margin: 70-85 percent.
For B2B services: COGS includes the fully-loaded cost of the service delivery team (consultants, project managers, account teams) and any direct costs of fulfillment. Typical B2B services gross margin: 40-70 percent.
For B2B industrial/manufacturing: COGS includes raw materials, manufacturing costs, freight, and direct labor. Typical industrial B2B gross margin: 20-40 percent.
Using contribution margin instead of gross margin inflates the apparent monthly gross profit per customer, which understates CAC payback and produces over-optimistic unit economics. Be strict about using true gross margin.
Healthy ranges by model
CAC payback benchmarks vary significantly by B2B model. The right benchmark to use is the one that matches your specific motion, not a generic average.
B2B SaaS: 12-18 months on MRR is healthy growth-mode. Under 12 months indicates aggressive growth potential. Over 24 months indicates a funnel problem that needs fixing before scaling.
B2B services: 6-12 months. Higher gross margins (typically 50-70 percent) and faster cash collection produce shorter payback expectations.
Industrial and manufacturing B2B: 18-36 months. Lower gross margins are offset by multi-year contracts and high retention rates.
Self-service / SMB B2B SaaS: Under 12 months. The lower ACV requires faster payback to maintain capital efficiency.
Enterprise B2B (ACV $100K+): 18-30 months. Longer sales cycles and higher CAC are offset by larger deal sizes and stronger retention.
If your CAC payback exceeds the upper end of your category by 50 percent or more, you have a unit economics problem. Marketing spend cannot fix it. The fix is positioning, ICP, pricing, or sales motion.
How to use the number
CAC payback period is most useful as a decision-making input for three specific questions.
Should we spend more on marketing? If CAC payback is healthy (within your category range), yes. Additional spend will likely produce additional revenue at acceptable economics. If CAC payback is broken, no. More spend amplifies the problem.
Which channels should get more budget? Channel-specific CAC payback tells you which channels actually compound. Channels with payback significantly below your category average should get more budget. Channels with payback significantly above should be cut or fixed.
Are we ready to scale? CAC payback that is healthy and stable across multiple quarters is the strongest signal that scaling is safe. CAC payback that fluctuates wildly (10 months one quarter, 22 the next) usually means underlying economics are not stable yet.
The mistake most B2B founders make is using CAC payback only at annual planning, when the number is too averaged to surface real problems. Use it monthly for budget decisions, quarterly for strategic decisions, and annually for fundraising or board discussions.
When CAC payback flagged a positioning problem
A $9M B2B SaaS company had blended CAC payback of 19 months, which looked acceptable for their category. Channel-specific breakdown revealed the real picture: paid search CAC payback was 12 months (healthy), but content-sourced CAC payback was 31 months. The blended number hid a serious problem in content marketing economics.
The diagnosis: their content was attracting buyers who liked the educational material but were not great fit customers. The fix was not to spend less on content. The fix was to sharpen positioning so the content attracted ICP buyers rather than browsers. Within 6 months, content-sourced CAC payback dropped to 14 months. The blended number reached 13. The change started with channel-specific CAC payback exposing a problem the blended number had hidden.
When CAC payback is broken
If your CAC payback exceeds the upper end of your category range by 50 percent or more, the underlying unit economics are broken. More marketing spend will not fix it. The fix is structural.
Diagnostic questions to ask first:
Is positioning the problem? If buyers do not self-select clearly into your category, you spend more to acquire each customer. Sharpen positioning before adding budget.
Is ICP the problem? If your sales team is closing customers who do not fit (because they pay), CAC inflates and retention drops. Realign on ICP and reject misfit customers, even if it temporarily reduces revenue.
Is pricing the problem? If gross margin is too thin, even reasonable CAC produces broken payback math. Test price increases with new customers before assuming the cost side needs to change.
Is the sales motion the problem? If sales is closing inefficiently (too many touches per deal, low close rate, long cycle), CAC inflates without revenue offsetting it. Fix the motion before adding marketing spend.
Most $5M to $50M B2B companies with broken CAC payback have problems across two or three of these areas. The fix is usually 6-12 months of focused work on positioning, ICP, pricing, and sales motion together rather than one at a time.
Where CAC payback breaks down
CAC payback is the right metric for most B2B companies most of the time. It is not perfect. Two situations where it can mislead: companies with very long contract terms (3+ year deals) and companies in growth-investment mode.
For companies with multi-year contracts, total contract value matters more than monthly revenue. CAC payback calculated on TCV often makes more sense than CAC payback calculated on monthly revenue. For companies in heavy growth investment mode (think venture-backed Series B), CAC payback can be artificially long because they are deliberately spending ahead of revenue. The metric still matters but needs to be interpreted alongside LTV/CAC ratio and growth rate. Outside these specific cases, CAC payback is the cleanest single metric for B2B unit economics health.
The starting point
Calculate CAC payback period this week. Use the actual formula (total CAC divided by monthly gross profit) and include every cost component honestly. Most B2B companies discover their real CAC payback is 30-60 percent worse than what they have been reporting. That is the starting point for real budget decisions.
Then break it down by channel, by customer segment, and by cohort. The blended number is useful as a top-line health check, but the channel-specific and segment-specific numbers are what drive actual decisions.
If you want help running this analysis, book a free 60-minute GTM diagnostic. We will walk through your CAC inputs, identify common calculation errors, segment payback by channel and cohort, and tell you where the highest-leverage improvements are. The diagnostic itself often produces the two or three changes that move CAC payback by 20-40 percent.
Frequently asked questions
Direct answers to what B2B leaders typically ask after reading this.
Most B2B companies miscalculate CAC.
Get the real number first.
Book a free 60-minute GTM diagnostic. We'll walk your unit economics and tell you what's actually working.
Book a Free Diagnostic →